
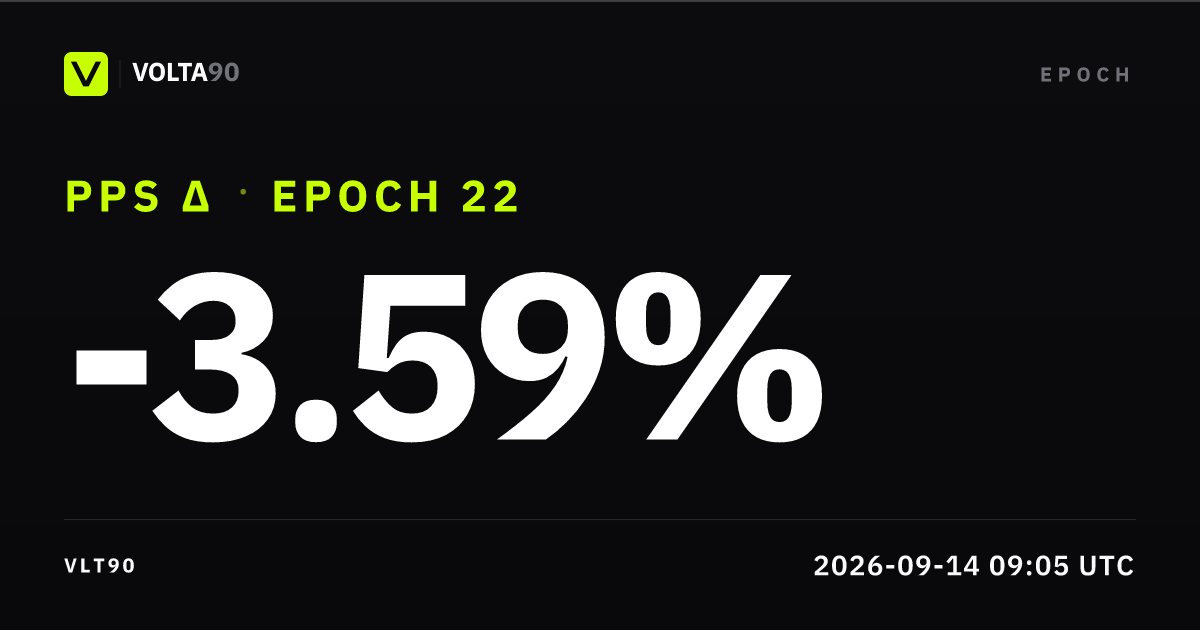
Epoch card
Operator desk note
During the week of September 7 to 13, there was a noticeable weakening in equities, particularly those related to semiconductors and AI. In contrast, financial and brokerage sectors, along with cryptocurrencies, showed relative strength. This market behavior underscores a prevailing theme of sector rotation that has been significant this year. However, the current stress around interest rates is not conducive to the appreciation of riskier assets like equities and cryptocurrencies.
Volta's strategy involved reducing exposure to high-beta stocks last week and plans to further cut positions in these sectors at the start of this week. This decision aligns with the typically unfavorable seasonality of September for equities and the anticipation of significant events: the Clarity Act for cryptocurrencies on September 15 and the U.S. Federal Reserve's interest rate decision on September 16. Additionally, geopolitical tensions in the Middle East are exerting upward pressure on oil prices, creating an environment that does not favor a risk-on approach.
Despite these challenges, Volta's portfolio has wisely maintained a lower market exposure in recent weeks. Consequently, no major changes in exposure will be made until there is clarity from the outcomes of the Clarity Act and the Fed's rate decision, along with an initial view of the ensuing price action. Should market flows turn more positive following these critical events, the strategy may consider increasing exposure to the finance and cryptocurrency sectors.
Performance
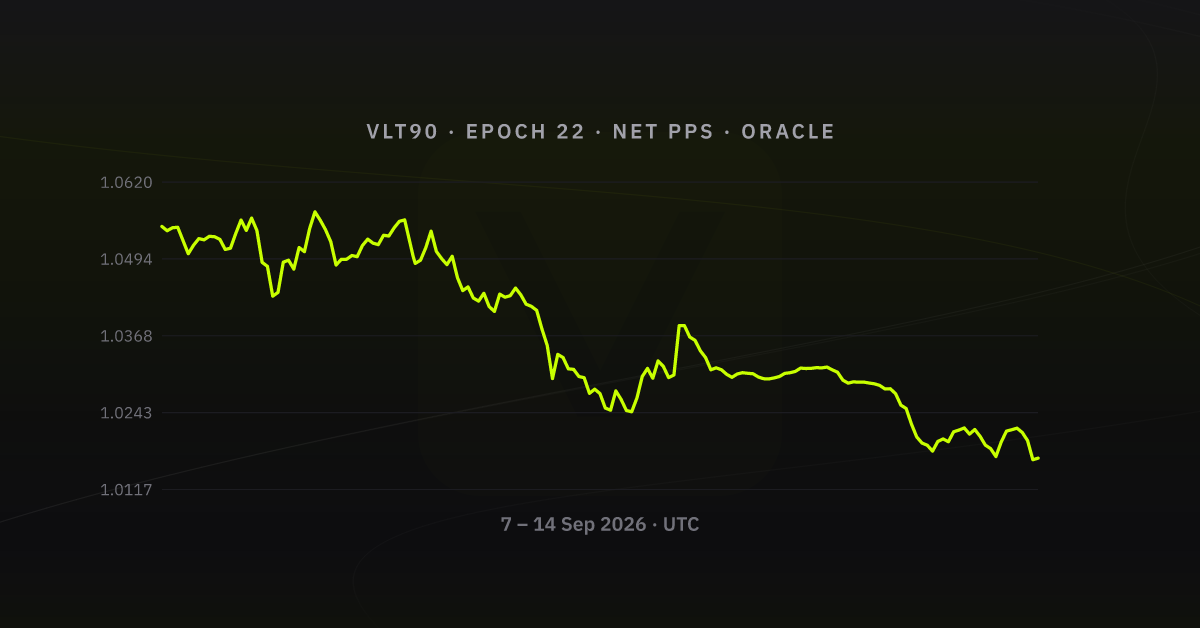
Over 2026-09-07 → 2026-09-14, net share price printed low 1.016589 and high 1.057093. The largest drawdown from a running intra-week high landed at 3.83%. That is the clearest stress point on the path. Volatility showed up in the band: low to high spanned ~3.84% versus week-open net PPS. Into the last tick, PPS sat meaningfully below week open (≈ -3.59%), a soft weekly finish. Open Performance in the app for the same net PPS basis with full zoom.
What drove the week
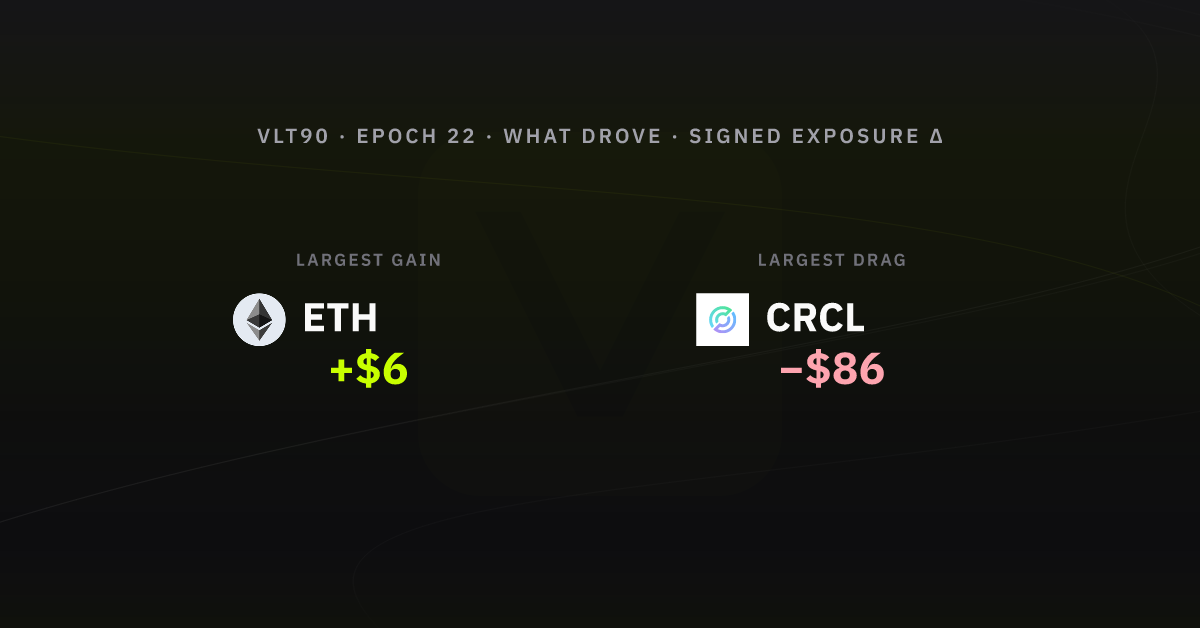
From week-open to week-end oracle snaps (cash sleeves excluded; perps: Δ unrealised P&L; spot: notional), sleeve-level marks moved most in favour of  ETH +$6 and most against
 CRCL −$86. Week 22 (2026-09-07 → 2026-09-14) landed almost no consolidated Hyperliquid clips in this export, so the story here is mostly marks and routing. The epoch card and appendix still anchor the week; consolidated clips will appear in the table below when the export carries ladders.
Allocation by asset class & gross exposure
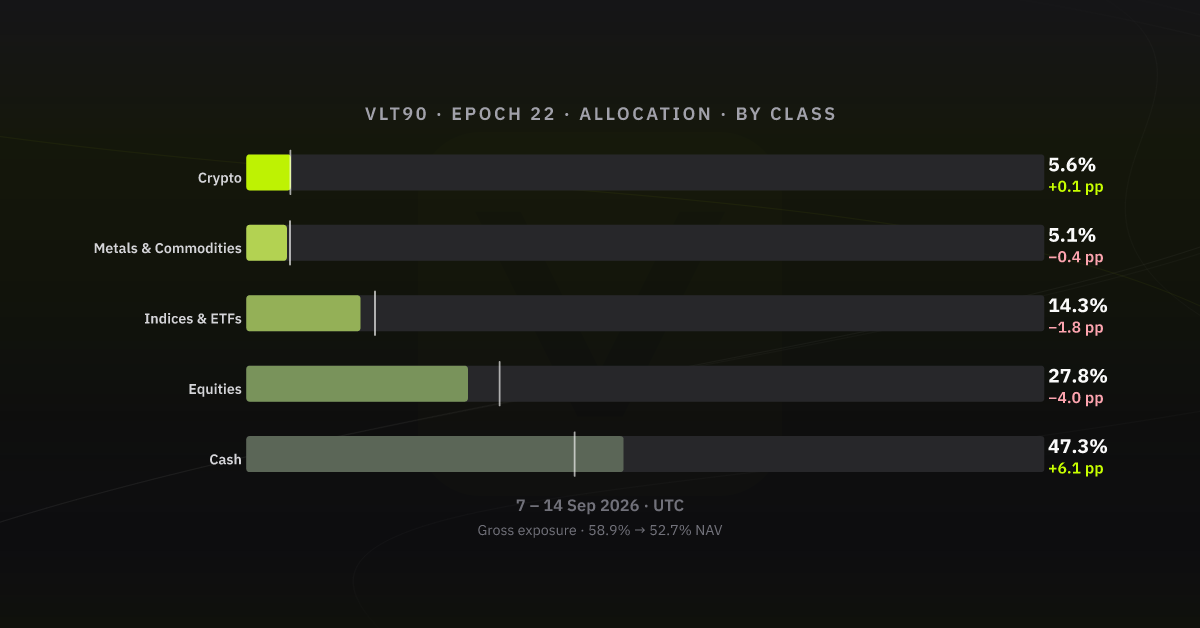
The clearest sleeve moves vs week open are Cash +6.1 pp, Equities −4.0 pp, and Indices & ETFs −1.8 pp. Gross exposure (deployed notional / NAV) moved from 58.9% to 52.7% of NAV. (-6.1 pp on gross exposure vs prior week-end). Same asset-class bands as Allocations (History tab); figures are % of vault NAV.
Listed clips: Hyperliquid
| Time (UTC) | Instrument | Side | Size | Price | Fee | Realised close P&L |
|---|---|---|---|---|---|---|
| - | No fills in window | - | - | - | - | - |
Realised P&L on closes. Nothing in the table above is a closing trade with booked profit or loss. Only opens, adds, or spot legs.
Appendix - sources & verification
GET http://127.0.0.1:3000/oracle/VLT90/epochs
GET http://127.0.0.1:3000/oracle/VLT90/snapshots?sort=asc&limit=1000&from=[epoch-open]&to=[epoch-close]
POST GraphQL PeriodSummary (vault week anchor; indexer endpoint in volta ops docs)
| Check | Value |
|---|---|
| Merged activity (this export) | 0 timeline events · 166 oracle snapshots in-window |
| Boundary multisig txs (open → close) | 0x1012b82105fc3af1da9c59e4204b599ef5a927c23a0f3e9ef2afbab741f473a9 · 0xf6999eac858cd7bd1277e001526ac9ad0640145e77f1cc76892796a74b28861d |
| Snapshots bookends | _id 11212 → 11543 (166 epoch-window docs; performance chart 166 ticks from 2026-09-07) |
What this document is not: not the exchange's internal risk pack; statements follow chronological order on Volta's merged activity feed.